
Banking Frankfurt
Banking in Frankfurt covers the services that banks provide to households, businesses and institutional clients: holding deposits, extending credit, processing payments and arranging finance. Banking connects everyday money management with longer-term investment. A current account supports bills and wages; a business loan finances equipment or working capital; a corporate banking team helps a company manage liquidity across accounts, currencies and markets.
The banking sector combines customer relationships with financial risk management and transaction infrastructure. Retail banking serves individuals, corporate banking serves businesses, and investment banking helps clients raise capital or complete transactions. These activities use different products and specialist teams, but all depend on reliable records, funding and controls. Bank lending also creates deposit money; banks do not simply pass on a fixed stock of savings.
How bank services fit together
A bank account records a claim against the bank. Customers use accounts to receive income, save and make payments. Lending creates a separate obligation: the borrower must repay the credit under agreed terms. A bank therefore needs to assess repayment capacity, manage its own funding and hold capital against risks. Deposits, loans and payments belong to one balance sheet and operating system.
A banking relationship can extend beyond credit. A business may need foreign-exchange transactions, guarantees, cash management or access to securities markets. Capital markets provide another route to financing through instruments such as bonds and shares. Banking advice must distinguish the customer's financing need from the particular instrument offered.
Frankfurt's banking district and financial institutions
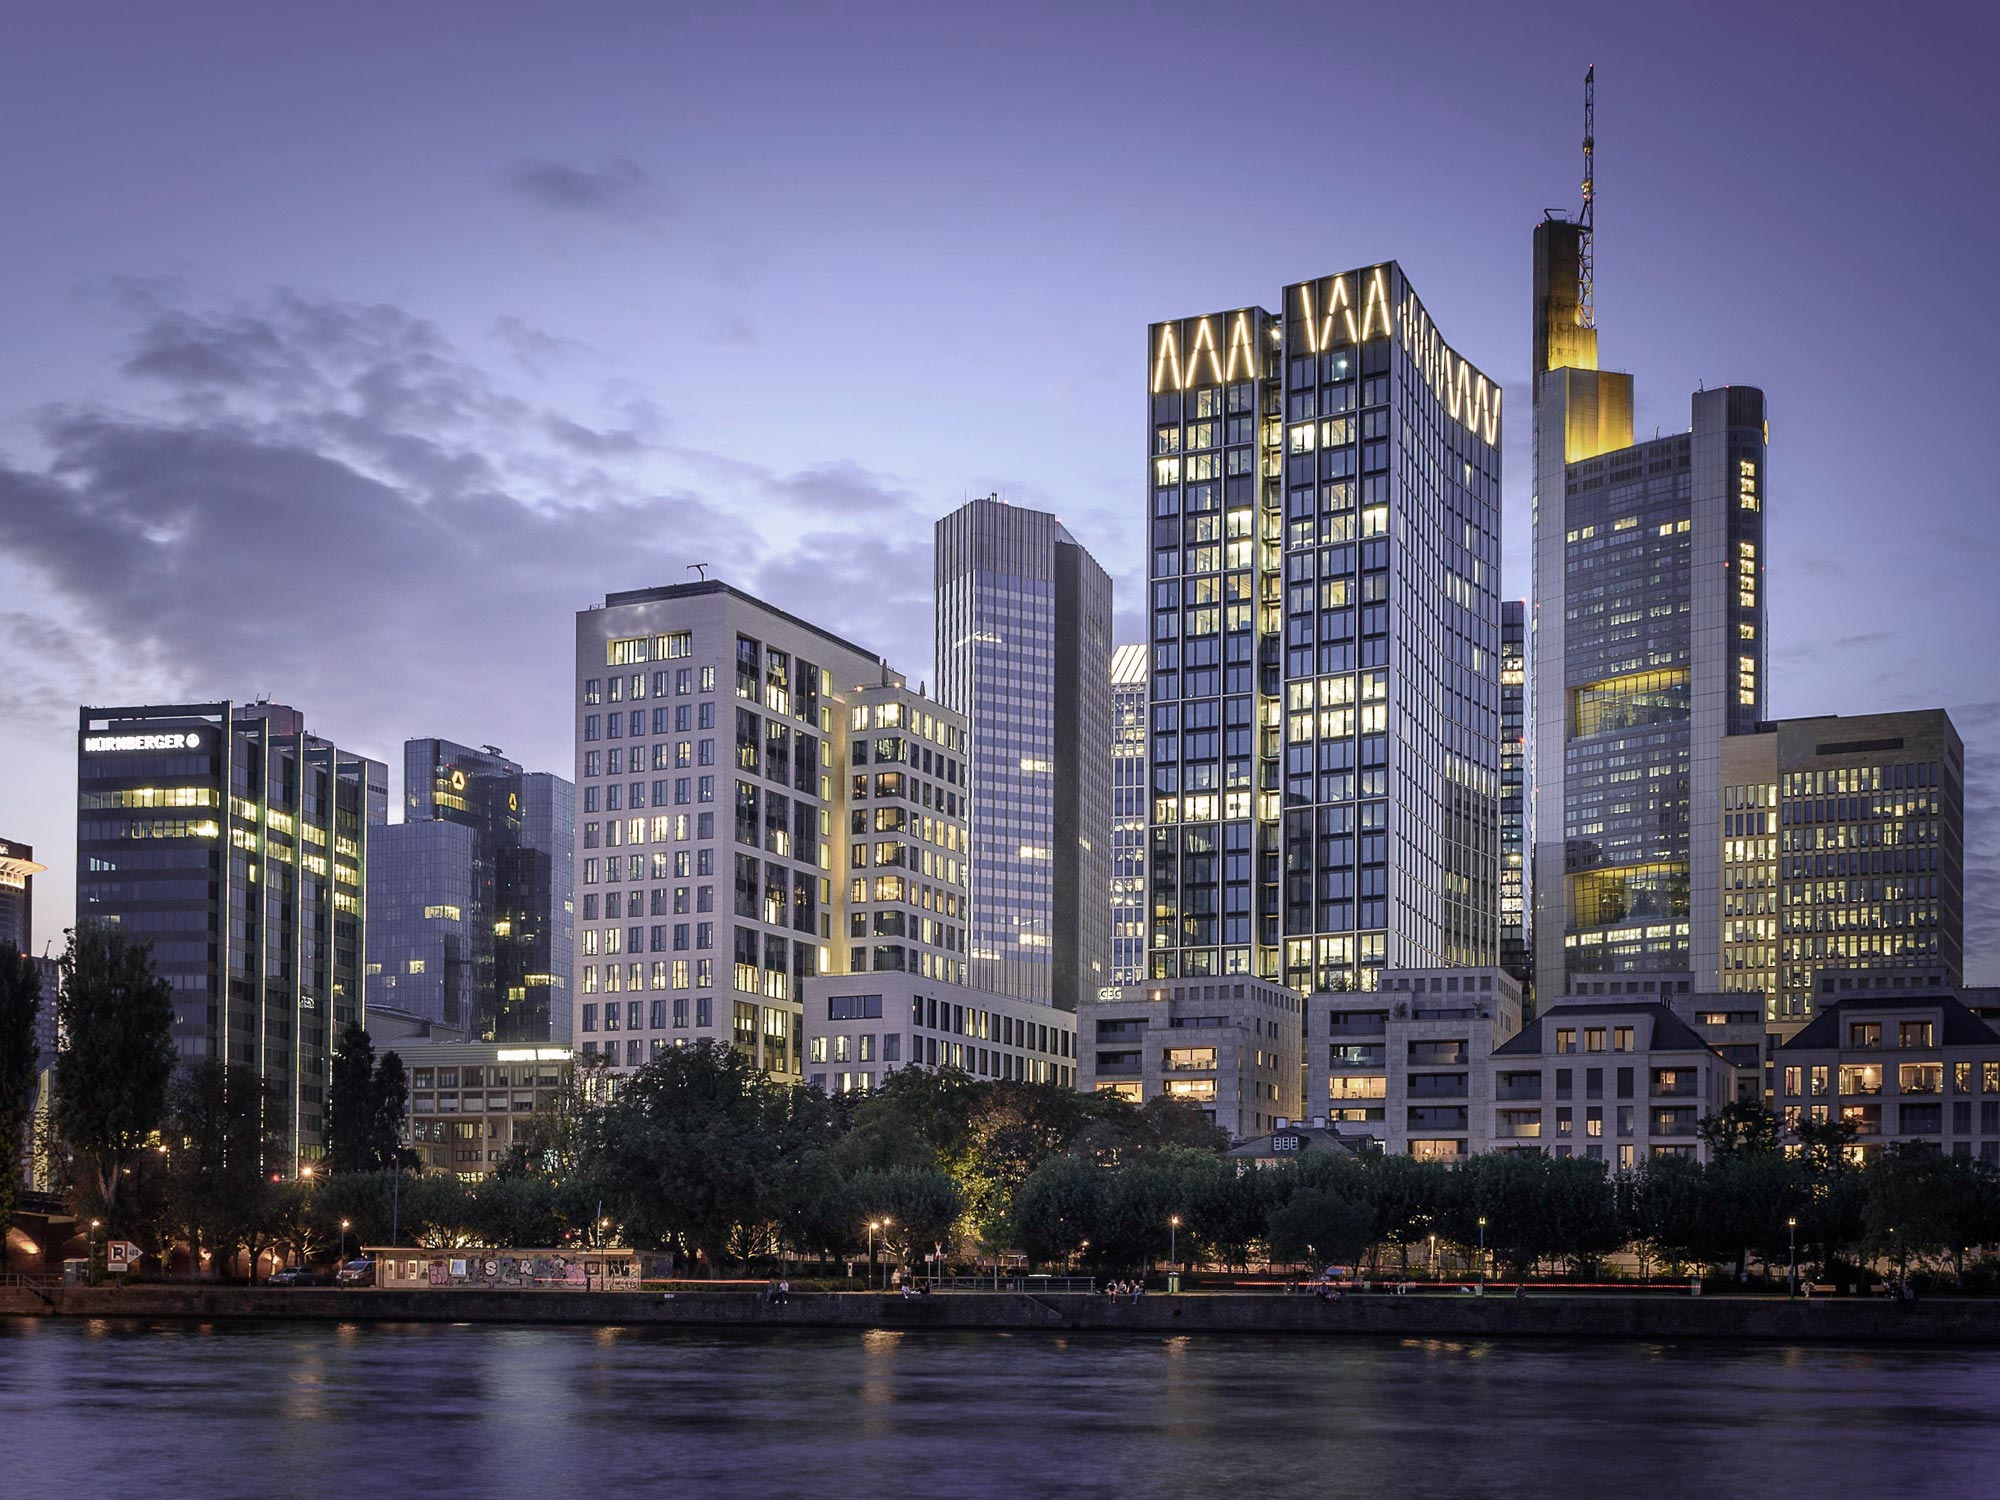
Frankfurt is a banking location within a wider financial center that also includes exchanges, asset managers, insurers and technology providers. Frankfurt is home to the European Central Bank and Deutsche Bundesbank. The region has an international banking sector (in German). International banks use Frankfurt for business with German and European customers, alongside institutions serving regional households and companies.
The banking district describes a concentration of offices, not a separate category of banking license or customer protection. A Frankfurt address does not determine whether a firm accepts deposits, issues loans or only supplies software. The institution's authorized activities and the relevant contracting entity matter when evaluating a service.
Business finance and payment settlement
Corporate banking links financing with a company's cash flows. A loan for machinery has a different repayment profile from a short-term facility covering the period between purchasing goods and receiving customer payments. The Frankfurt Chamber of Commerce (in German) treats bank credit as an important part of business financing, alongside wider financial services. A productive discussion starts with the purpose, duration and risks of the financing.
Payments require infrastructure beyond the customer's app. The Eurosystem's T2 system settles large-value payments in central bank money. A customer account balance at a commercial bank is different from a bank's balance at a central bank. Keeping those forms of money separate helps explain why a payment involves account entries, messages and settlement between institutions.
Commercial banks, central banks and supervisors
Commercial banks serve customers and take business risks. Central banks have monetary policy and central banking responsibilities. Banking supervisors assess the safety and soundness of supervised institutions. Frankfurt brings these functions into the same city, but the functions are not interchangeable. The ECB separates its banking supervision from monetary policy.
Within European banking supervision, the ECB directly supervises significant institutions. National competent authorities directly supervise less significant institutions under ECB oversight. The allocation follows the supervisory framework, not the location of a bank's office. A Frankfurt bank is therefore not automatically directly supervised by the ECB.
Capital, liquidity and credit risk
Lending exposes a bank to the risk that a borrower fails to meet an obligation. Capital provides a buffer against losses. Liquidity concerns the ability to make payments when they fall due. Liquidity regulation seeks to preserve that ability. A long-term claim can retain its value without providing the cash immediately needed to make a payment.
These distinctions matter when assessing banking activity. For a loan, repayment capacity, collateral and maturity are relevant; for the bank's funding, the timing of potential outflows also matters. Through the Supervisory Review and Evaluation Process, or SREP, supervisors examine business models, governance, risks to capital, and liquidity and funding risks. Looking only at product features or a banking app misses these financial relationships.
Banking and technology events in Frankfurt
Is Frankfurt banking the same as investment banking?
Investment banking is one part of banking in Frankfurt. Capital raising and transaction advice differ from retail accounts, corporate lending and payment services. A bank can offer several lines of business, but an investment banking service does not by itself include a deposit account.
Does a digital banking platform make a company a bank?
A software platform is not a banking authorization. Technology can support accounts, payments and controls, but the regulated institution remains responsible for its permitted business. The distinction between the software supplier and the institution providing the financial service matters for customers and project teams.
Payments & Digital Money
Risk & Compliance
Banking Frankfurt and Finance Loop
Finance Loop connects banking, payments, IT and AI professionals. Finance Loop organized the Finance Meets Emerging Technologies side event at Sibos on payments, blockchain technology and institutional digital assets, presented by Frankfurt Main Finance and OKX Institutional, in cooperation with TechQuartier and EDITH. Finance Loop also organized an official AI Week Frankfurt finance side event with sessions on financial crime investigation and AI testing.
Finance Loop is a professional network and has the goal of driving the adoption of emerging technologies in finance, such as AI, digital payments, cloud and blockchain solutions. Finance Loop helps its members build skills and personal networks in these fields: Investment & Digital Assets, Payments & Digital Money, Digital Infrastructure & Sovereignty, and Risk & Compliance.