
Accessible Banking
Accessible banking means that people with disabilities can use ATMs, payment terminals, banking apps and bank websites independently. Banking interfaces must work with assistive technology and present information people can understand. Spoken instructions, tactile keys and accessible digital controls help customers complete banking tasks without assistance.
Accessible banking gives customers access to their money and payment services when standard interfaces create barriers. Since 28 June 2025, the European Accessibility Act and national implementing laws set requirements for covered products and consumer banking services. Banks and technology providers need to consider accessibility throughout the service, including identification and payment approval.
What the European Accessibility Act covers in banking
The law firm Travers Smith lists the consumer banking services in scope: credit agreements including consumer loans and mortgages, payment services, services linked to a payment account, electronic money and certain investment services. Websites and apps for these services must be perceivable, operable and understandable, and must work with assistive technology. Information about the service must not go beyond the upper intermediate level of the Council of Europe's language framework (CEFR).
The service exemption applies to microenterprises with fewer than ten employees and either annual turnover or an annual balance sheet total of no more than 2 million euros. The service exemption does not remove the accessibility requirements for products such as ATMs. Member states set the penalties, and in serious cases products and services that do not comply can be withdrawn from the market.
ATMs and payment terminals
The German implementing act identifies the covered hardware: its first section lists payment terminals with their hardware and software, and ATMs, among the self-service terminals that must be accessible when they are placed on the market after 28 June 2025. The same act also covers banking services provided to consumers.
Transition periods apply to older equipment, and under section 38 of the German act, a bank may keep providing its services with products it lawfully used before 28 June 2025 until 27 June 2030. Self-service terminals already in use may stay until the end of their economic life, but no longer than 15 years after they were first put into operation. The directive itself allows up to 20 years, as Travers Smith notes.
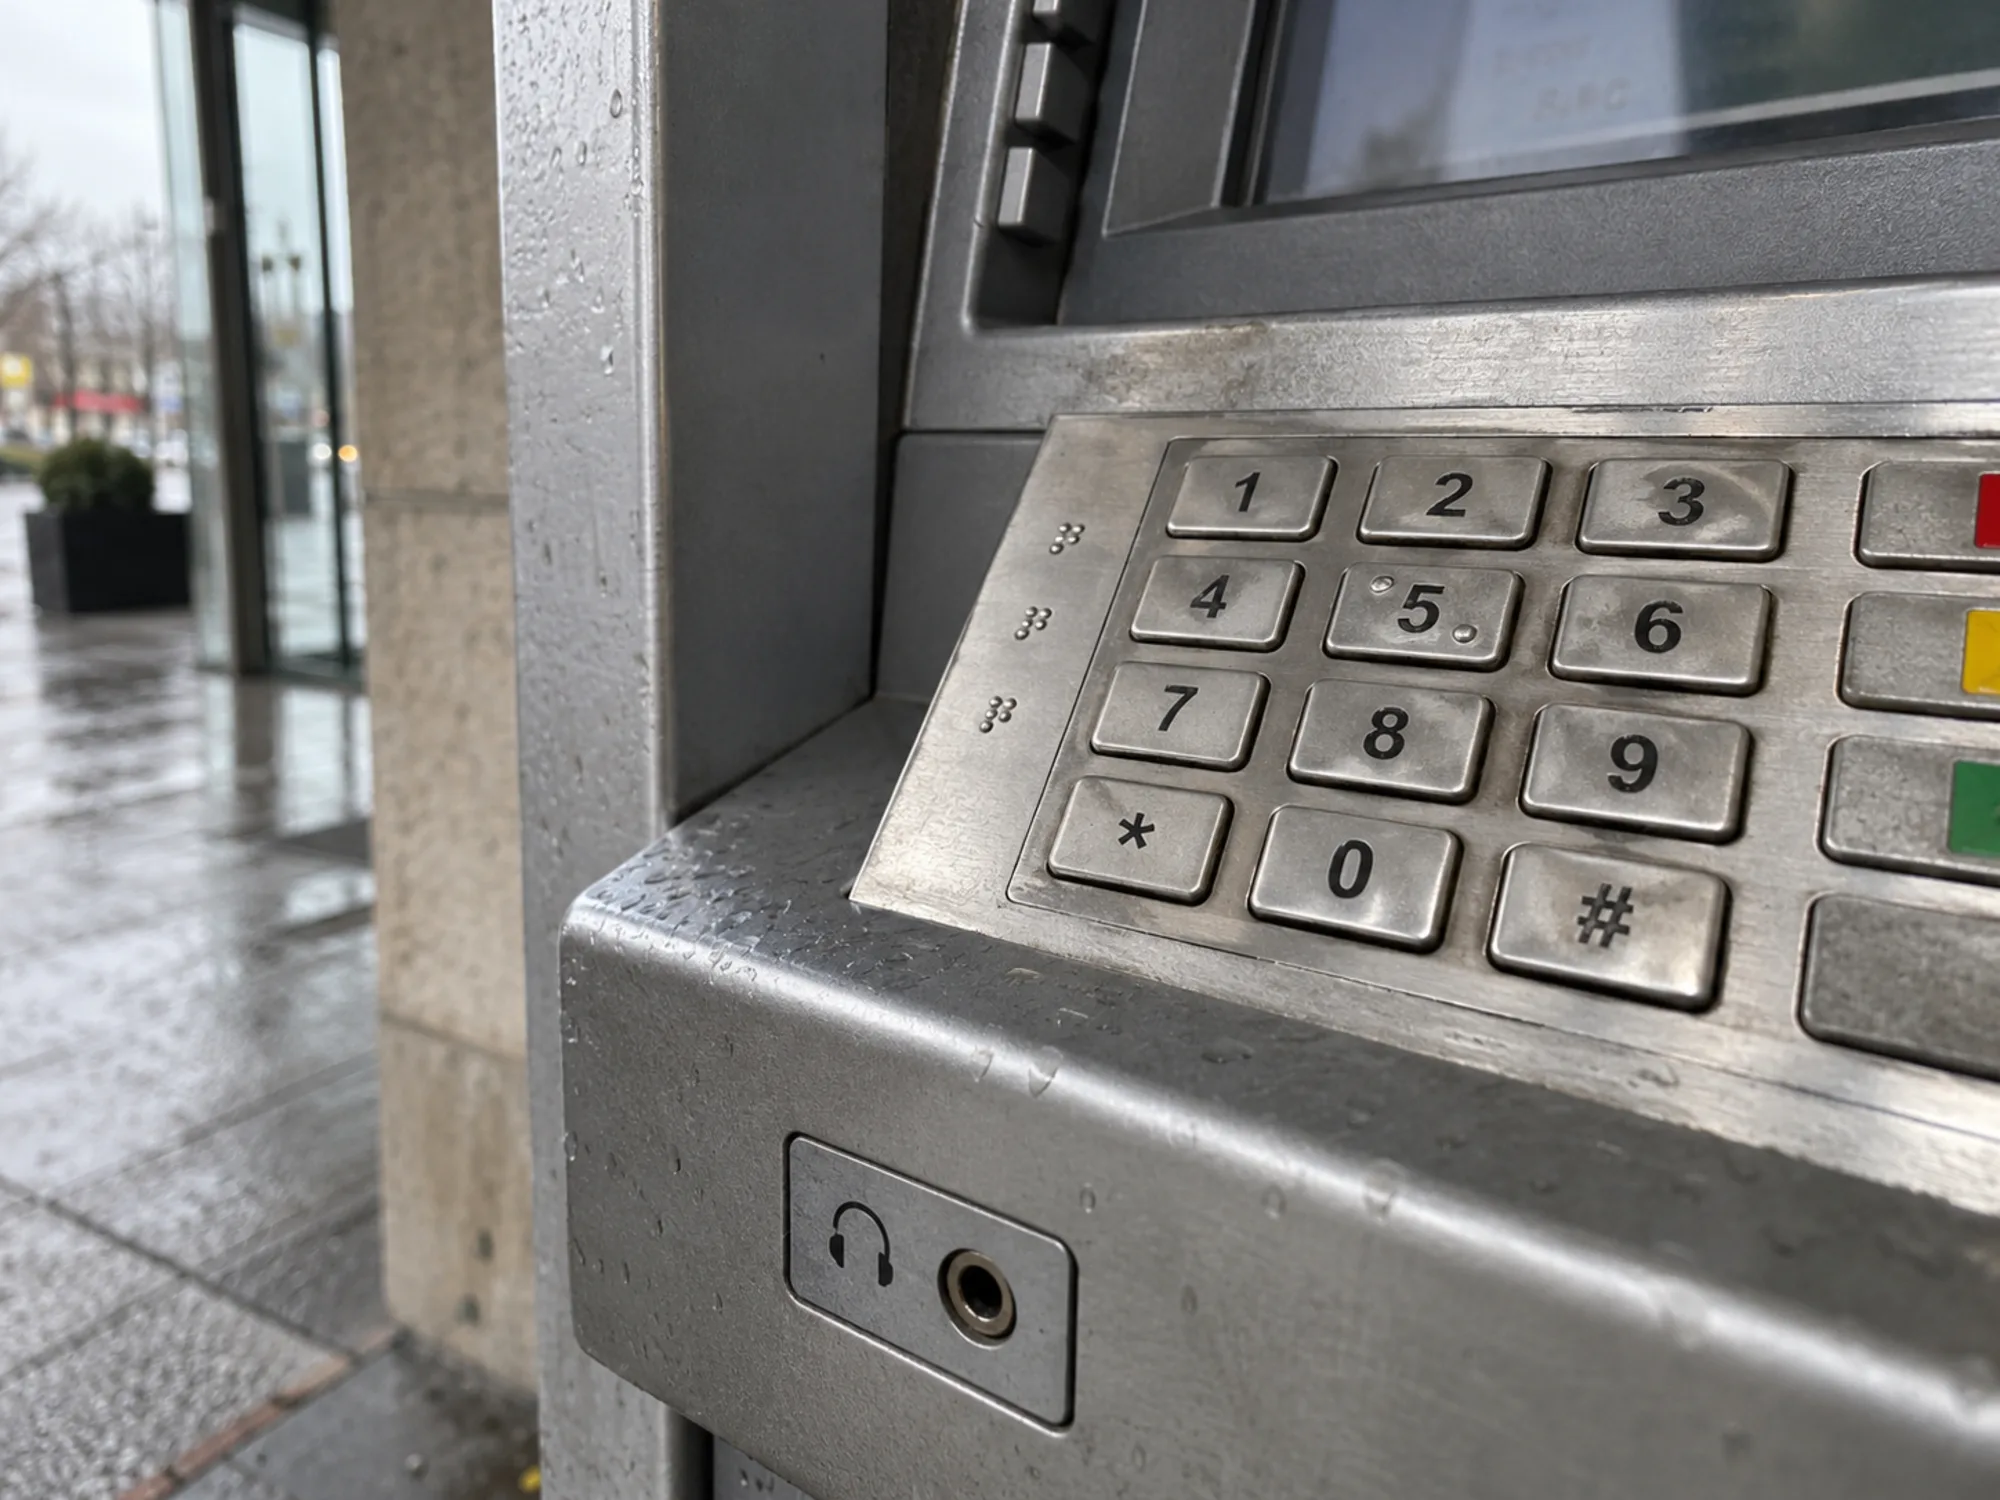
At the machine, accessibility includes spoken instructions, a connection for personal headphones and enough time to respond. Where a keypad is provided, its keys need adequate contrast and tactile cues. Users must be able to activate these features without first navigating an inaccessible menu. These requirements are set out in Annex I of the European Accessibility Act.
Banking apps, digital identity and payment approval
According to Travers Smith, identification methods, electronic signatures, security features and payment services must meet the same requirements. In practice that covers opening an account remotely by video identification or eID, approving a payment in the banking app, and signing a credit agreement electronically.
Upcoming payments events in Germany
Finance Loop and accessible banking
Payment terminals, banking apps and the rules for them belong to the Payments & Digital Money track at Finance Loop. The payments regulation page covers the other rules that payment providers in Germany follow, and the access to cash page covers the ATM network.
Payments & Digital Money
Risk & Compliance
What does accessible banking mean?
Accessible banking lets people with disabilities use banking services without help: ATMs and payment terminals they can operate, and websites and apps that work with assistive technology and use plain language.
Does the European Accessibility Act apply to banks?
The European Accessibility Act covers consumer banking services such as credit agreements, payment services, payment accounts, electronic money and certain investment services, plus ATMs and payment terminals placed on the market after 28 June 2025.
How long can old ATMs stay in use?
In Germany, old ATMs can remain in use until the end of their economic life, at most 15 years after first use, while the directive allows up to 20 years. Services built on older products may continue until 27 June 2030.
Are small payment providers exempt?
Yes, for services covered by the European Accessibility Act. Under Articles 3 and 4, a microenterprise has fewer than ten employees and either annual turnover or an annual balance sheet total of no more than 2 million euros. This exemption does not apply to products such as ATMs.
Accessible banking and Finance Loop
Finance Loop covers accessible banking in its Payments & Digital Money track, next to payment terminals, access to cash and digital identity. Finance Loop brings people from banks, payment institutions and terminal providers together at events in Frankfurt, Munich, Berlin and Hamburg.
Finance Loop is a professional network supporting the institutional use of emerging technologies in finance, such as AI, digital payments, cloud and blockchain solutions. Finance Loop helps its members build skills and personal networks in these fields: Investment & Digital Assets, Payments & Digital Money, Digital Infrastructure & Sovereignty, and Risk & Compliance.