
ESG risk management
ESG risk management examines how environmental, social and governance factors affect the financial risks a bank already manages. Climate change and the transition to a lower-carbon economy can change the value of collateral and a borrower's ability to repay. Banks need to identify these effects so that lending and risk decisions reflect exposures over different time horizons.
The EBA guidelines set requirements for identifying, measuring and managing ESG risks, including risks from the transition to a climate-neutral economy. In Germany, BaFin supervision and the MaRisk framework also address how banks handle these factors. The assessment covers their effects on credit, market, liquidity and operational risks across the bank's activities.
The EBA guidelines on ESG risks
The European Banking Authority published its final guidelines on 9 January 2025, based on the amended Capital Requirements Directive. They apply to large institutions from 11 January 2026 and to small and non-complex institutions from 11 January 2027 at the latest. They set out how banks identify, measure, manage and monitor ESG risks, and they require plans that address the risks from the transition toward the EU's goal of climate neutrality by 2050, over the short, medium and long term.
According to the summary from KPMG, the materiality assessment runs every year, or every two years for small and non-complex institutions. Banks combine exposure-based, portfolio-based and scenario-based methods, and their transition plans carry timelines, intermediate targets and milestones. A separate set of EBA guidelines covers environmental scenario analysis.
How MaRisk treats ESG risks
In Germany, section 25a of the German Banking Act names ESG risks among the risks a bank must manage over the short, medium and long term, and section 26c deals with them directly. The current MaRisk says it specifies section 26c and implements both EBA guidelines, on ESG risk management and on environmental scenario analysis.
MaRisk defines ESG risks as events or conditions from the environment, social or governance areas that act as drivers of the existing risk types. Banks assess their effects in the risk inventory, the internal control system, the strategy and the reports, on plausible scenarios that agree with scientific findings; data history alone is not enough. The ninth amendment dropped the duty to use several methods to identify them.
Climate risk at the large banks
The significant banks follow the guide from the European Central Bank on climate-related and environmental risks from 2020. KPMG notes that these banks were expected to meet its expectations by the end of 2024, that progress differs between institutions, and that the ECB keeps using enforcement measures against banks that fall short. The ECB also runs climate stress tests with horizons beyond three years.
The priority areas KPMG lists are physical risks from extreme weather and biodiversity loss, transition risks such as stranded commercial real estate, greenwashing and litigation, and ESG risks in supply chains. For a lender these turn into data questions: the energy rating of a building in the collateral file, the emissions of a corporate borrower, the flood zone of a property.
Upcoming events on risk and compliance
What are ESG risks for banks?
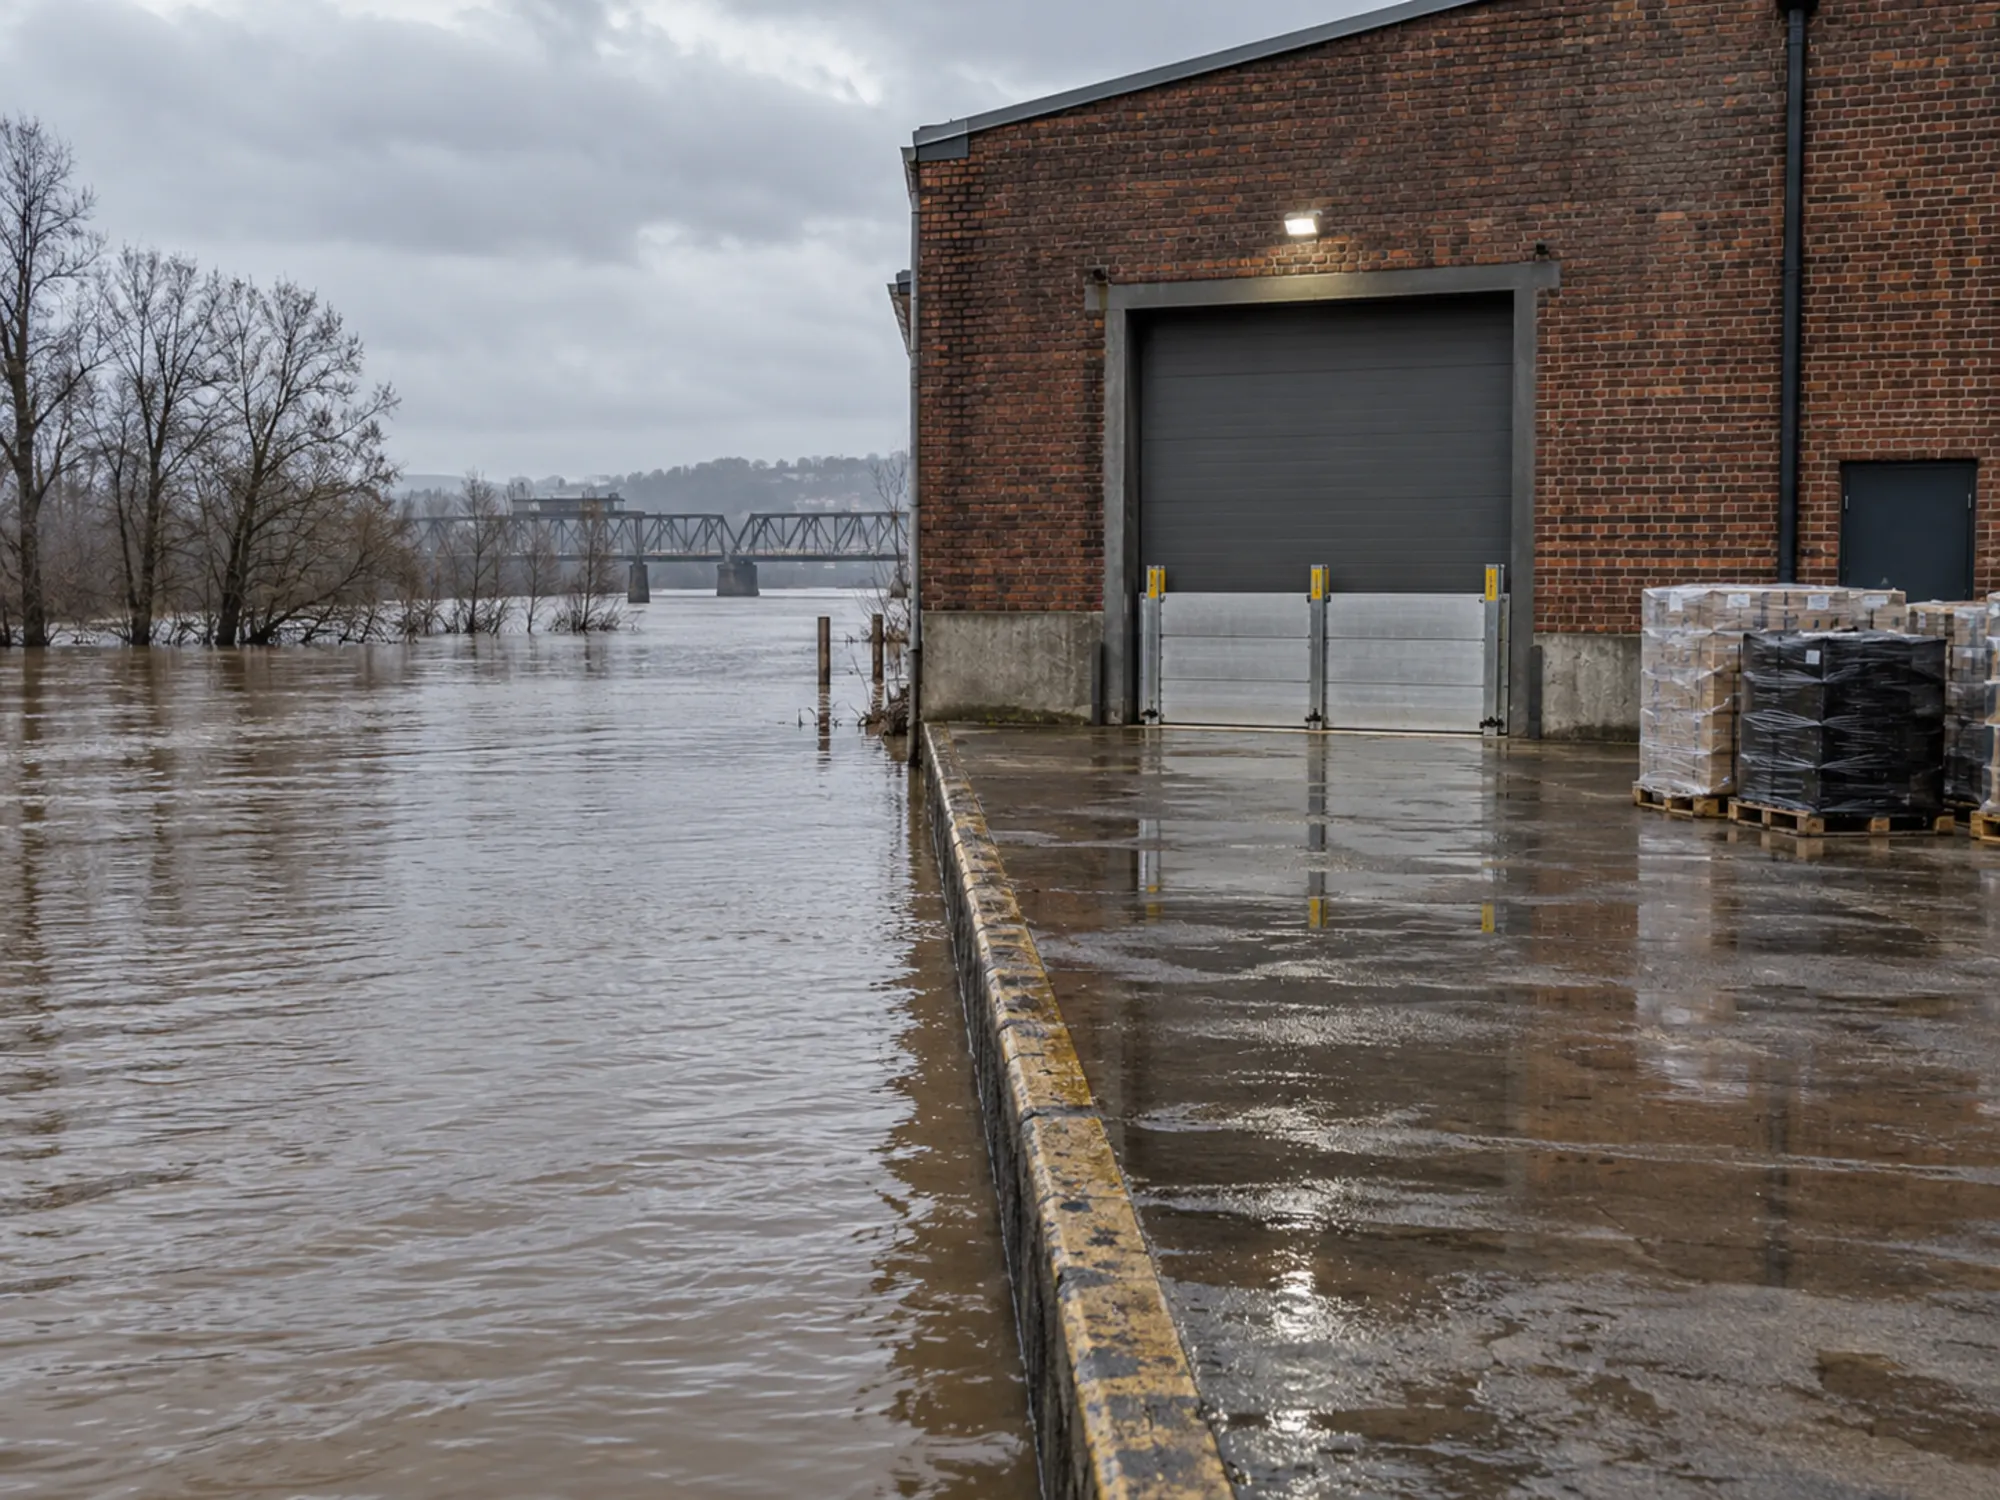
ESG risks come from environmental, social or governance factors and show up in the bank's own risk types. A flood damages the collateral behind a mortgage, a carbon price makes a borrower's business less profitable, a governance scandal at a customer becomes a credit loss or a reputational problem. They are risk drivers, which is why MaRisk does not treat them as a separate risk type.
How is ESG risk management different from ESG reporting?
Risk management steers the bank: it decides which loans it grants, at which price, and how much capital it holds. Reporting discloses the result to the market, through the CSRD, the EU taxonomy and the bank's green asset ratio. The two use the same data, and ESG reporting in Germany covers the disclosure side.
Which risk types do ESG factors affect?
All risk types are affected: the summary from KPMG of the EBA guidelines lists credit, market, operational, liquidity and reputational risk, and the guidelines expect each of them to be assessed for ESG drivers over the short, medium and long term.
ESG risk management and Finance Loop
Finance Loop brings the credit risk managers, risk controllers and data teams who build ESG risk models together with the regtech firms that serve them. Finance Loop was media partner of the International Financial Standards Conference of Börsen-Zeitung in Frankfurt, where regulators, standard setters and auditors discussed ESG disclosure.
Finance Loop is a professional network supporting the institutional use of emerging technologies in finance, such as AI, digital payments, cloud and blockchain solutions. Finance Loop helps its members build skills and personal networks in these fields: Investment & Digital Assets, Payments & Digital Money, Digital Infrastructure & Sovereignty, and Risk & Compliance.