
Machine learning in finance
Machine learning in finance uses models that learn patterns from data to support decisions about financial activities. A model can estimate a borrower's default risk or flag a payment whose behavior differs from known cases. Banks and investment firms also use these methods to examine market information and test predictions.
Machine learning helps financial teams work through large amounts of data, but its results depend on the examples and assumptions used to build the model. A useful prediction must be tested against new cases and reviewed for errors. For a bank, the purpose of the model also determines the supervision and approval requirements that apply to its use.
What machine learning does in finance
Machine learning is the part of AI in which a model learns rules from data instead of having them written by hand. Finance has used statistical models for decades, and machine learning extends them to more data and non-linear patterns. Three families cover most uses.
Supervised learning predicts a known target from past cases: whether a borrower defaults, whether a card payment is fraud, whether a customer leaves. Unsupervised learning finds structure without a target, for example clusters of similar customers or transactions that look unlike all others, which is how many anti-money laundering tools flag cases. Reinforcement learning learns by trial and reward and is used in research on trading, hedging and portfolio choice. The textbook Machine Learning in Finance: From Theory to Practice by Matthew Dixon, Igor Halperin and Paul Bilokon is organized along these lines, with Python examples for algorithmic trading, investment, wealth and risk management, and gives almost half of its pages to reinforcement learning.
Machine learning for credit risk
Credit risk is where machine learning meets bank capital. A bank that calculates its capital requirements with the internal ratings-based (IRB) approach needs the supervisor's approval for each model. The European Banking Authority collected industry views on machine learning in these models and published a follow-up report on machine learning for IRB models. The EBA found that most banks intend to use machine learning in risk differentiation, mainly for probability of default models tied to credit decisions, and it set out recommendations for prudent use. The report also covers how IRB rules interact with the GDPR and the EU AI Act.
In Germany, the Bundesbank and BaFin consulted the industry on machine learning in risk models for Pillar 1 and Pillar 2, with explainability and data as the main questions. A machine learning credit scoring model for private customers is also high-risk under the EU AI Act, so it needs human oversight, documentation and bias testing on top of the prudential rules. The hub answer on credit risk explains probability of default and the other basics.
Fraud detection, trading and asset management
Fraud detection is one of the oldest uses. A model compares each payment with the customer's usual behavior and holds the ones that do not fit, and section 25h of the German Banking Act requires banks to run such monitoring whether the model is rule-based or learned. The EU AI Act expressly keeps fraud detection out of its high-risk credit scoring line. The fraud prevention in Germany page covers the details. Insurers use the same methods for claims fraud and for pricing, and pricing in life and health insurance is high-risk under the AI Act.
In trading, machine learning models forecast prices and volumes, and firms use them inside algorithmic trading strategies. MiFID II applies whatever model drives the algorithm, and the firm must be able to stop it at any time; the algorithmic trading in Germany page sets out the rules. In asset management, ESMA's survey of EU securities markets found that portfolio optimization and trading with AI are still rare compared with text and coding tasks, as the AI in asset management page shows.
Learning machine learning for finance
For a full degree, Frankfurt School of Finance & Management runs a part-time Master of Artificial Intelligence & Data Science over four semesters, as the data science in finance page explains. Many practitioners start with Python, a machine learning library and a finance data set, then take a course or a book such as the one by Dixon, Halperin and Bilokon. Model validation teams at banks ask for the same skills from the other side: they test whether a model is stable, fair and explainable before it goes live.
Upcoming machine learning and finance events
Finance Loop, the meeting place for machine learning in finance
Finance Loop is the meeting place for quants, data scientists, risk modelers and model validators who use machine learning at banks, insurers and asset managers. Finance Loop connects the finance, IT and AI communities in Germany, Austria and Switzerland, with events in Frankfurt, Munich, Berlin and Hamburg.
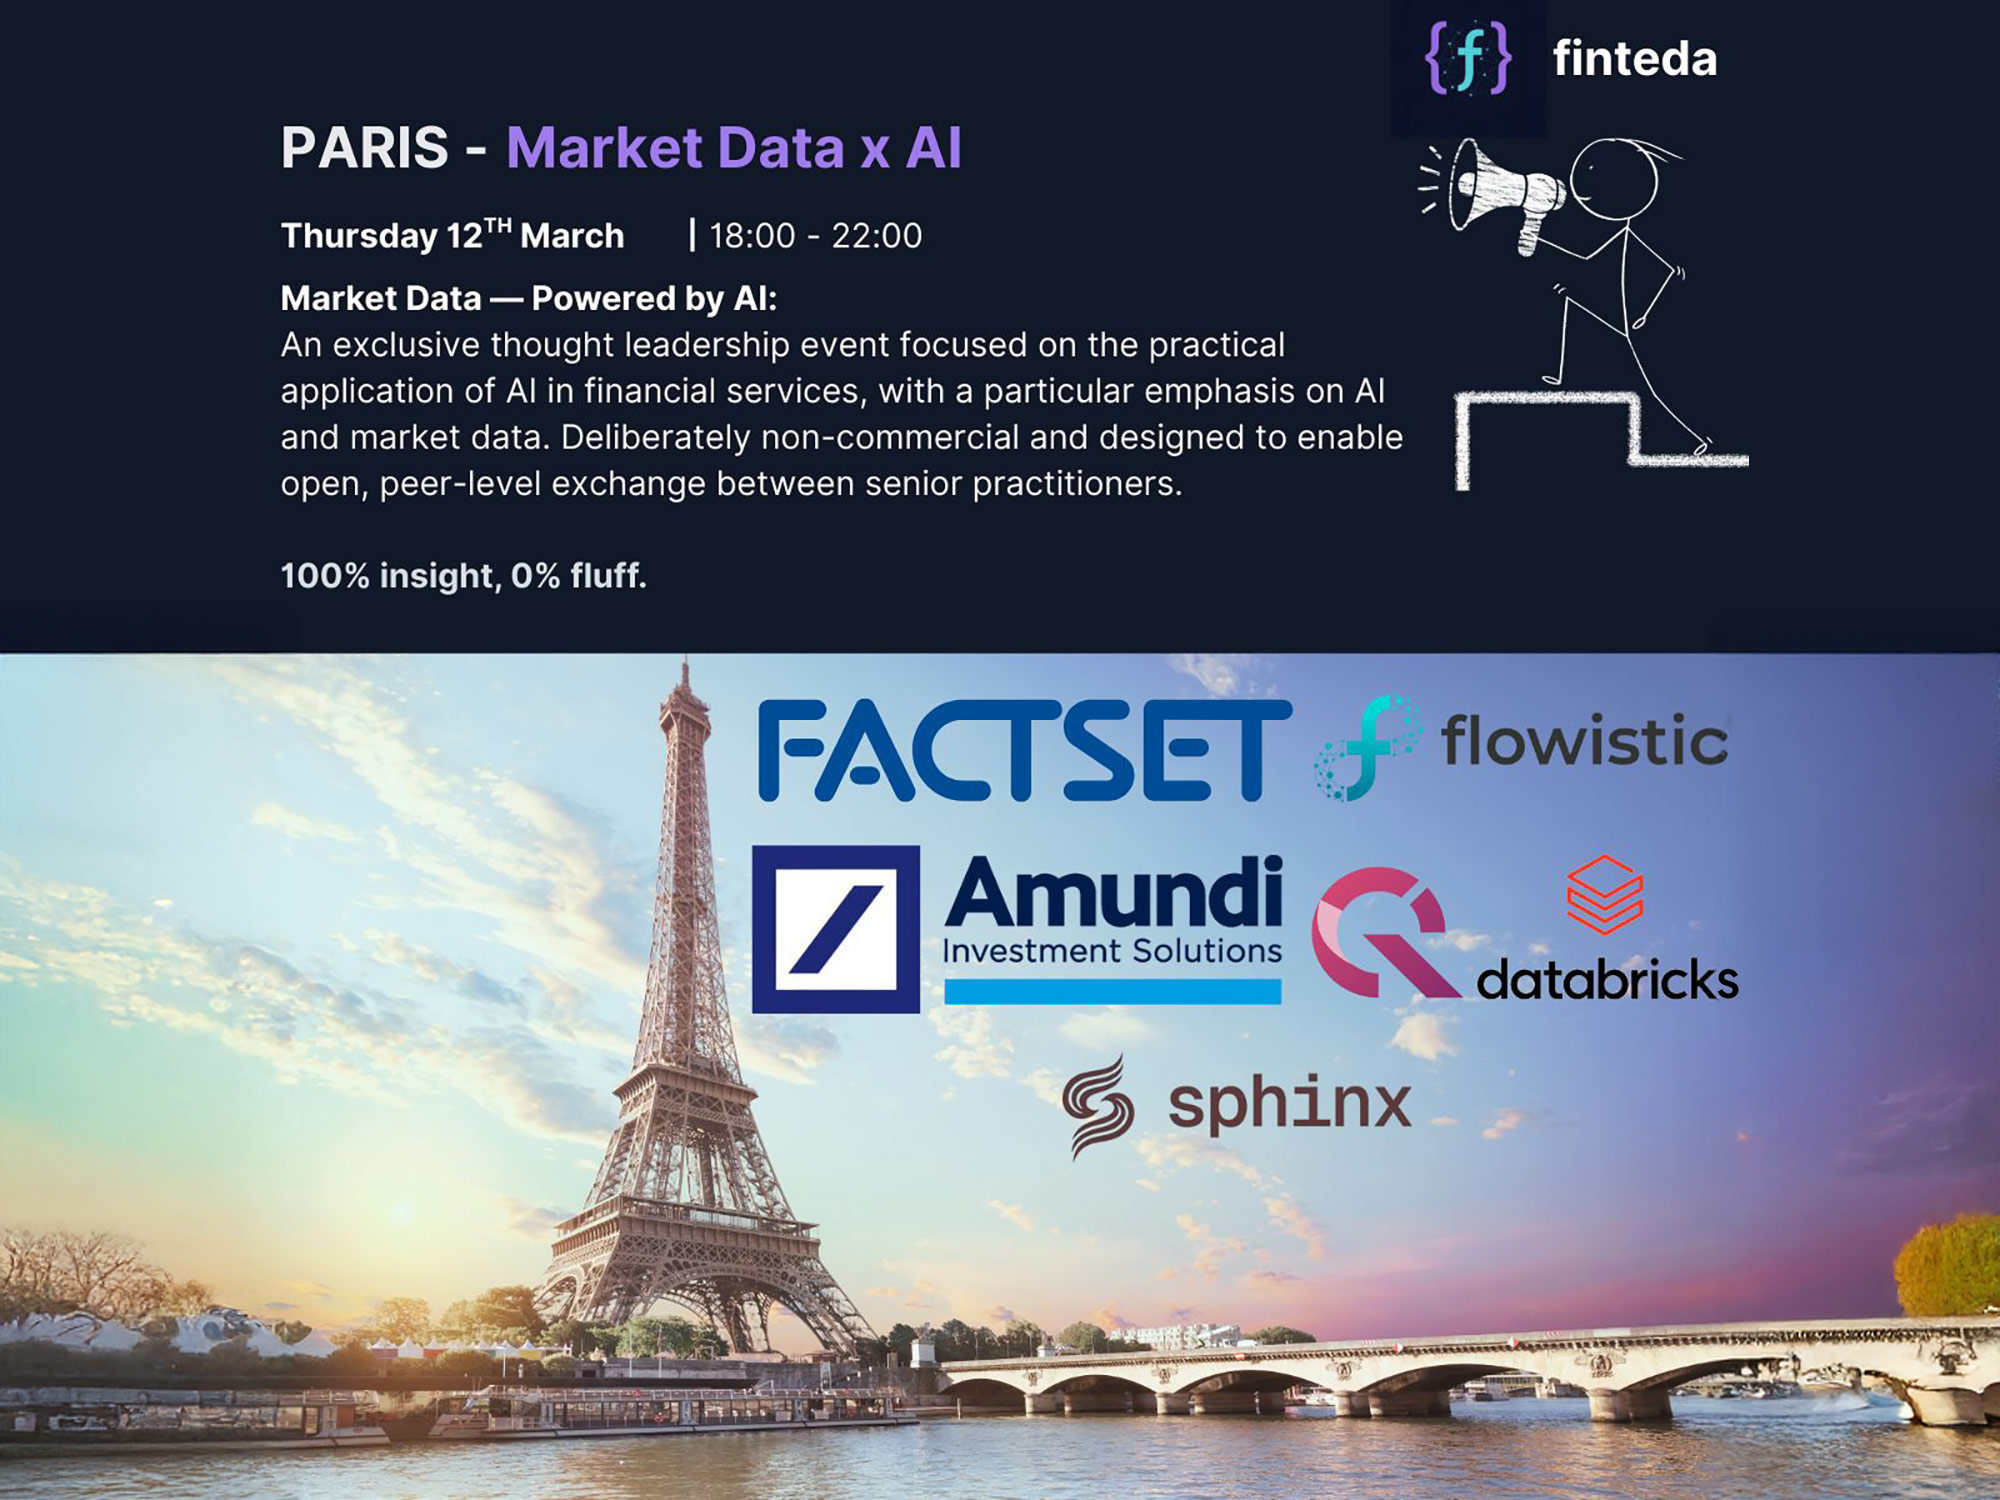
Finance Loop supported the AI & Financial Market Data meetup in Paris, where quantitative developers from Deutsche Bank compared market data architectures with people from Amundi, FactSet, QuestDB and Databricks. Finance Loop works with Finteda, whose program covers quantitative technology and machine learning, and with Frankfurt Data Science on applied data science meetups in Frankfurt. Finance Loop also organizes the Frankfurt Quantum Finance Forum with Frankfurt School, the Deutsche Bundesbank and IBM.
What is machine learning in finance?
Machine learning in finance is the use of models that learn from data to make or prepare financial decisions: credit scores, fraud alerts, price forecasts, customer segments. The model finds the pattern in past data, and people decide whether and how to use its output.
Can banks use machine learning for credit risk models?
Yes, with conditions. For capital models under the IRB approach, the supervisor must approve the model, and the EBA recommends prudent use with attention to explainability. For consumer credit scoring, the EU AI Act adds its high-risk duties.
Which book on machine learning in finance should I read?
Machine Learning in Finance: From Theory to Practice by Dixon, Halperin and Bilokon covers supervised learning, time series and reinforcement learning with Python code. For AI agents built on language models, Building AI Agents for Finance, co-written by Finance Loop member Fayssal El Mofatiche, is the newer reference.
Is there a machine learning in finance meetup in Frankfurt?
Frankfurt Data Science holds applied data science and AI meetups in the city, and Finance Loop lists its own and its partners' dates on the events page and in the calendar above.
Machine learning in finance and Finance Loop
Machine learning sits in the credit and fraud models of Risk & Compliance and in the trading and portfolio tools of Investment & Digital Assets. Finance Loop supported the AI & Financial Market Data meetup in Paris and organizes the Frankfurt Quantum Finance Forum.
Finance Loop is a professional network supporting the institutional use of emerging technologies in finance, such as AI, digital payments, cloud and blockchain solutions. Finance Loop helps its members build skills and personal networks in these fields: Investment & Digital Assets, Payments & Digital Money, Digital Infrastructure & Sovereignty, and Risk & Compliance.