
Micropayments
Micropayments are electronic payments for very small amounts, often cents or fractions of a cent. The method lets a customer pay for an individual digital item or a small unit of service, such as an article or an API call. Payment systems must process these amounts at a cost proportionate to the value transferred.
Providers use micropayments for pay-per-use services where usage can be measured in small units. The concept has a long history in digital publishing, while machine-initiated transactions create additional uses. Prepaid balances and grouped transactions are among the approaches used to manage the cost of collecting small payments.
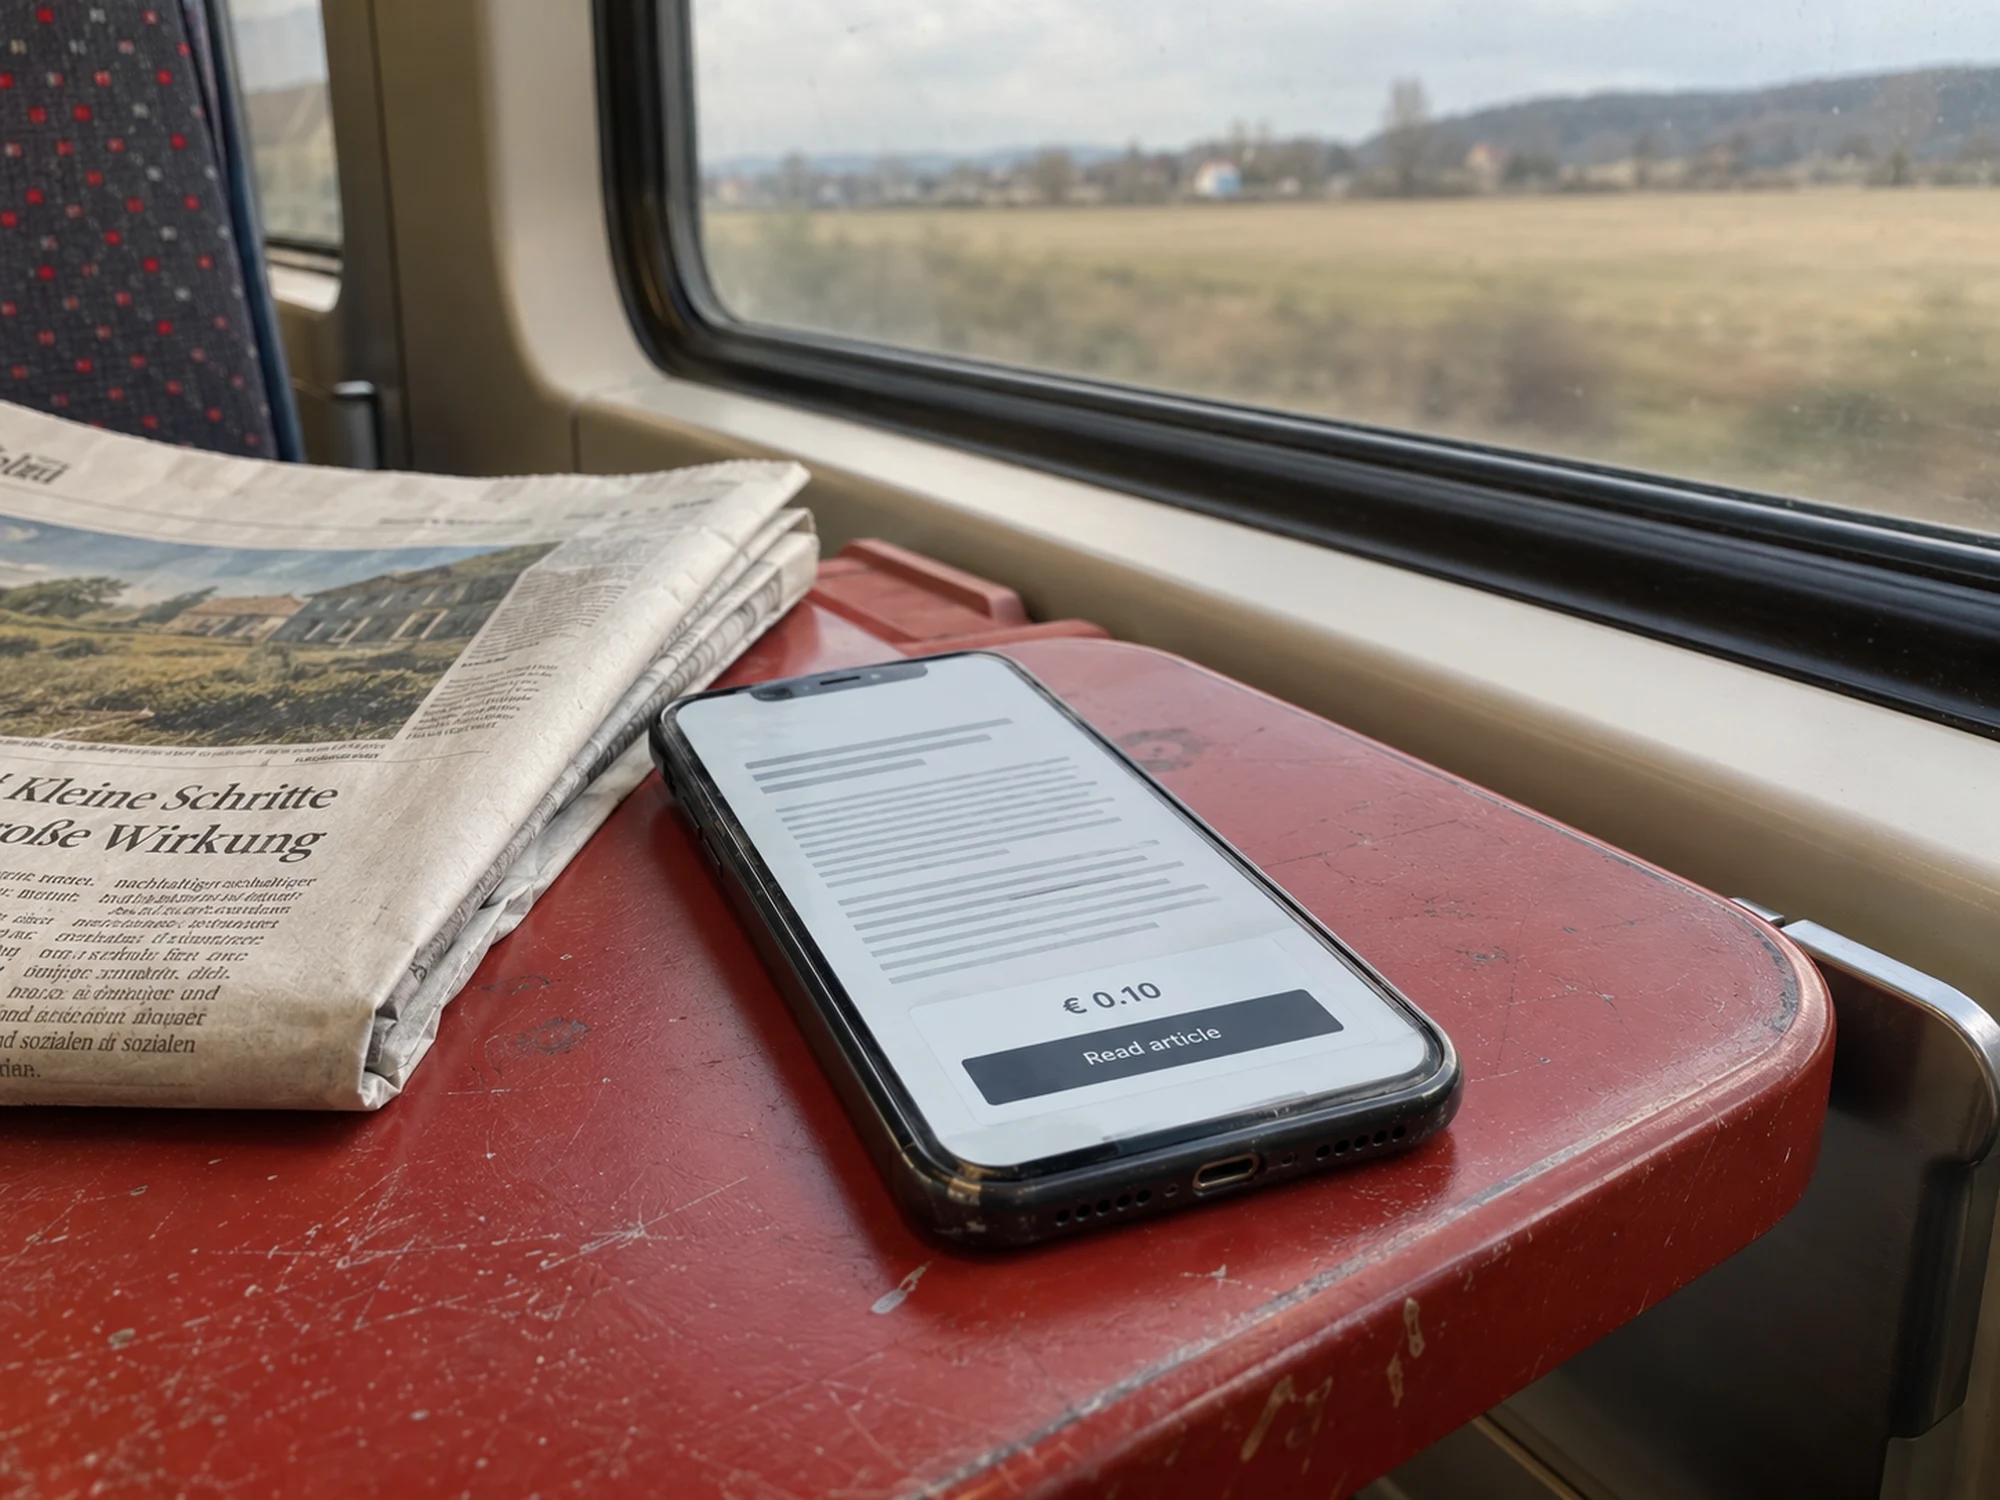
Why micropayments stayed rare
Ted Nelson coined the term, and early systems such as Millicent, presented in 1995, handled amounts from a tenth of a cent to five dollars. The W3C worked on a payment standard for HTML and stopped. News publishers tried pay-per-article models, and Blendle, the best known of them, moved to subscriptions in 2019.
The obstacle is the fixed cost per transaction. In the EU the Interchange Fee Regulation caps interchange at 0.2 percent for consumer debit cards and 0.3 percent for credit cards, but scheme and acquirer fees per transaction still make a ten-cent card payment uneconomic. Most sellers bundle small amounts into a top-up balance or one monthly bill.
Small amounts and strong customer authentication
Under PSD2 every online card or bank payment needs strong customer authentication unless an exemption applies. The regulatory technical standards exempt remote payments of up to 30 euros, as long as the cumulative amount since the last authentication stays at or below 100 euros or the count at five payments. Contactless payments at a terminal are exempt up to 50 euros. A stream of small online payments therefore still triggers an authentication every few transactions.
Strong customer authentication covers the rules in full. For micropayments the practical answer has been the wallet with a stored balance, where the authentication happens once at top-up and the small payments move inside the provider.
Stablecoins, x402 and payments by software
The new demand comes from software. AI agents and applications buy data and computing time per request, and a human authentication per request does not fit. x402 lets a server answer a web request with a price and lets the client pay in a stablecoin within the same exchange.
For European banks and payment institutions the question is whether these flows stay on stablecoin rails or move to euro rails. SEPA Instant settles in seconds but carries a cost per transaction, and the digital euro proposal caps the fees merchants may be charged. Machine-to-machine payments shows the same trade-off for devices.
Upcoming payments events in Germany
Why are micropayments expensive?
Each payment carries a fixed processing cost, from scheme and acquirer fees to fraud checks. On a payment of a few cents that cost can exceed the amount, so providers aggregate small payments into larger charges.
Can stablecoins make micropayments viable?
Stablecoins on low-cost networks can move amounts below one cent, and protocols such as x402 build payment into web requests. The open points are the conversion to and from euros and the anti-money laundering duties of the provider.
Micropayments and Finance Loop
Finance Loop covers micropayments in its Payments & Digital Money track, where card acquirers and AI developers compare what a payment of a few cents costs on each rail. Finance Loop events bring these groups together in Frankfurt and other cities.
Finance Loop is a professional network supporting the institutional use of emerging technologies in finance, such as AI, digital payments, cloud and blockchain solutions. Finance Loop helps its members build skills and personal networks in these fields: Investment & Digital Assets, Payments & Digital Money, Digital Infrastructure & Sovereignty, and Risk & Compliance.