
Tokenized Bonds
A tokenized bond represents a debt security as a digital token on a blockchain or another distributed ledger. The issuer owes payments to investors under the bond's terms, such as interest and repayment at maturity. Tokenization concerns how the security is recorded and transferred, while the bond's terms define the investor's claims against the issuer.
Recording a bond on a distributed ledger can connect issuance, trading and settlement within a shared system. Issuers and financial institutions use this approach to coordinate the delivery of securities with payment. The settlement time depends on the infrastructure and transaction arrangements; using a blockchain does not by itself make every trade settle immediately.
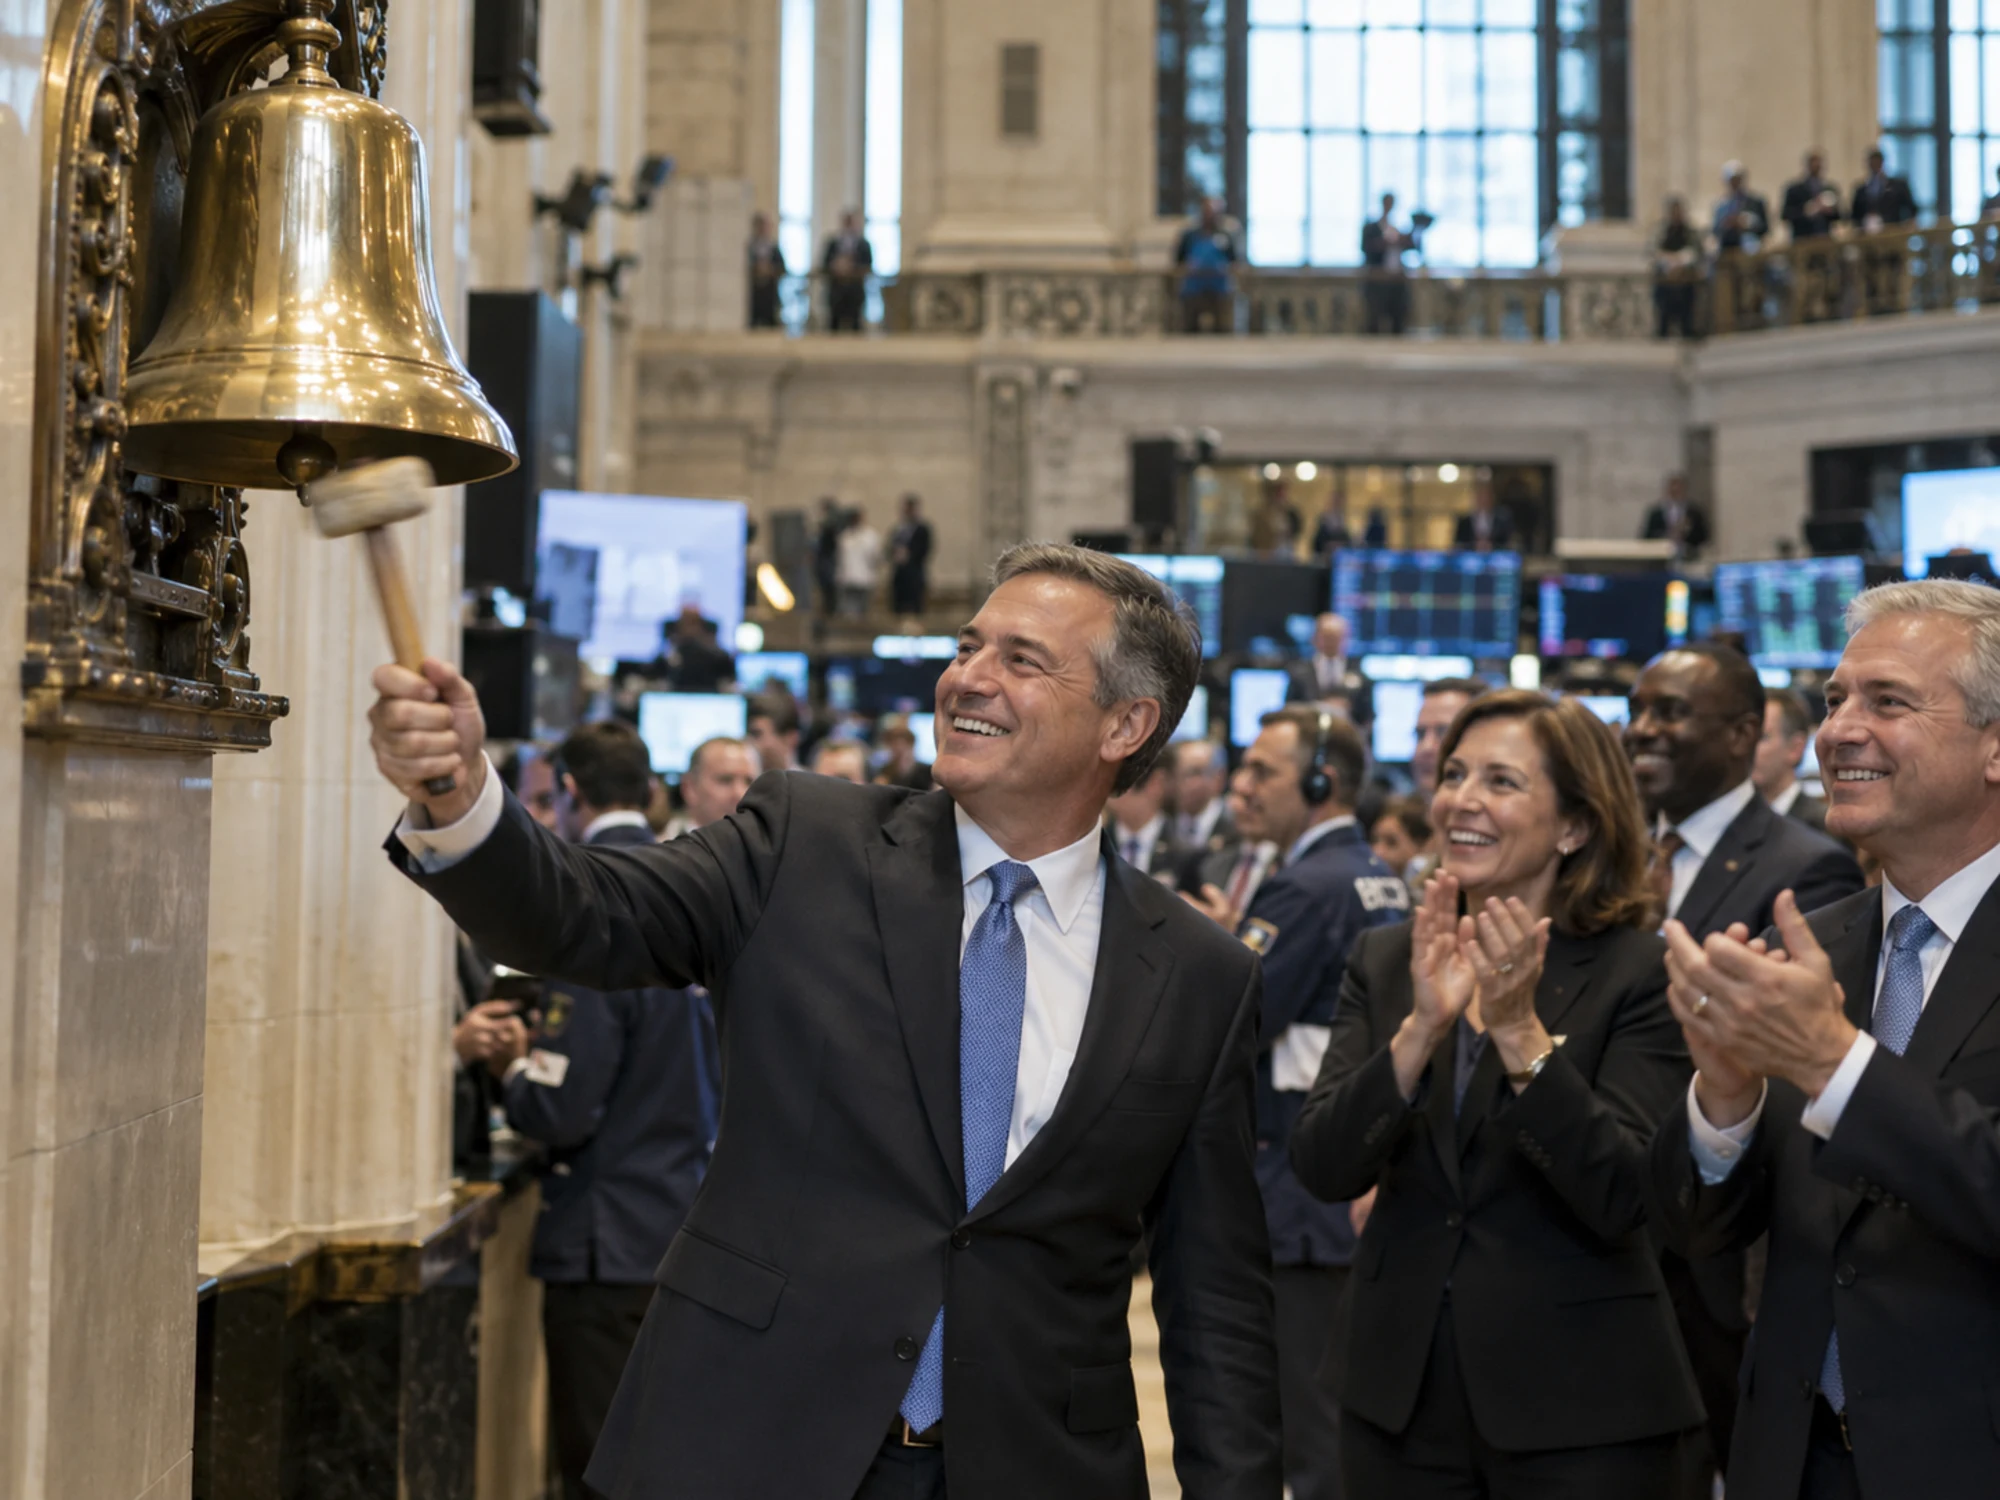
How a bond settles today
When an investor buys a bond, the trade goes through a central securities depositary such as Clearstream, which holds the official register of who owns what and moves the entries between custodian banks once a trade is confirmed. Cash and securities move on separate rails that have to be coordinated so that neither side pays or delivers before the other, and the current standard cycle for most securities trades executed on EU trading venues requires settlement no later than two business days after the trade (T+2). The EU transition to T+1 applies from 11 October 2027. This system moves trillions of euros a year across German and European markets, but every step, from the paying agent to the depositary to the custodian, adds a handoff and a reconciliation point where a mismatch can delay settlement.
What a tokenized bond changes
Germany's Elektronische Wertpapiergesetz (eWpG), in force since 2021, lets an issuer create a bond as an electronic security without a paper certificate, including as a crypto security recorded on a blockchain. The bond keeps its coupon, its maturity and its legal claim on the issuer; only the register that proves ownership and the process that moves that ownership change. When the register and the cash settlement both run on the same infrastructure, the trade can settle as soon as both sides confirm it, instead of waiting for the standard cycle. Repo trades benefit the most from this speed: a bond used as overnight collateral several times in one day frees up sooner for its next trade when settlement takes minutes instead of a full business day. Christoph Hock, Head of Tokenisation and Digital Assets at Union Investment, makes the same case from the investor side in his foreword Tokenisation and the next chapter of capital markets for the International Capital Market Association (ICMA): on a DLT-based bond, coupon payments and redemptions run automatically, and one ledger carries the security from issuance and trading through settlement and servicing.
The Siemens digital bond and the Bundesbank's Trigger Solution
Siemens issued a 300 million euro digital bond in 2024 on the private blockchain of the fintech SWIAT, with Deutsche Bank, DZ Bank and DekaBank among the participating banks. The Deutsche Bundesbank's Trigger Solution settled the cash leg in central bank money, linking the blockchain-based securities settlement to the Bundesbank's own payment system so the trade cleared with the same finality as a conventional bond. 360X, a Frankfurt trading venue holding one of the EU's few licenses under the DLT Pilot Regime, Regulation (EU) 2022/858, carried out the bond's first secondary-market trade between DekaBank and Union Investment. The deal ran as part of the European Central Bank's wholesale DLT settlement trials, which put a real bond through blockchain-based issuance, secondary trading and central bank money settlement in sequence.
The legal questions a tokenized bond still has to answer
A tokenized bond still has to answer what happens to ownership if a private key is lost, how a court enforces a claim recorded on a blockchain, and how the token interacts with insolvency law if the issuer defaults. The eWpG and the DLT Pilot Regime answer these questions by naming a registrar or a market operator that carries legal responsibility for the record; a token always has an accountable party behind it. Cross-border recognition is the harder open point: a tokenized bond issued under German law still needs other jurisdictions to recognize the same ownership record if an investor outside Germany wants to trade it. Hock also chairs ICMA's DLT Bonds Working Group, which published the DLT Bonds Reference Guide, more than 50 practical questions on the lifecycle of a DLT-based bond, written for bond desks and digital asset teams.
Upcoming digital asset events in Germany
Finance Loop and tokenized bonds
Tokenized bonds and market infrastructure were on the program of the Frankfurt Forum on Digital Assets & Applications, where DekaBank, 360X, 21X and Seturion discussed DLT market infrastructure, and of the Crypto Assets Conference of Frankfurt School and Deutsche Börse, a conference Finance Loop has partnered with. 21X, a partner of Finance Loop, runs a DLT venue for tokenized stocks, bonds and funds. Tokenized bonds sit in Finance Loop's Investment & Digital Assets track, next to its tokenized funds and RWA content. Related pages: RWA tokenization, tokenized funds and tokenization in Germany.
Investment & Digital Assets
What is a tokenized bond?
A tokenized bond is a bond whose ownership record and settlement process run on a blockchain instead of through a conventional central securities depositary. The bond itself carries the same coupon and maturity as a conventional bond; only the way ownership is recorded and transferred changes.
Has a German company issued a tokenized bond?
Yes. Siemens issued a 300 million euro digital bond in 2024, settled in central bank money through the Deutsche Bundesbank's Trigger Solution, with Deutsche Bank, DZ Bank and DekaBank among the banks involved and a first secondary trade executed on the Frankfurt venue 360X.
What law allows a bond to exist only as a blockchain entry in Germany?
The Elektronische Wertpapiergesetz (eWpG), in force since 2021, allows a bond or other security to exist as an electronic security, including a crypto security recorded on a blockchain, without a paper certificate. A registrar named under the law carries legal responsibility for the ownership record.
Tokenized Bonds and Finance Loop
Tokenized bonds and market infrastructure were topics at the Frankfurt Forum on Digital Assets & Applications, where DekaBank, 360X, 21X and Seturion spoke on DLT market infrastructure, and at the Crypto Assets Conference of Frankfurt School and Deutsche Börse, a conference Finance Loop has partnered with. Tokenized bonds sit in Finance Loop's Investment & Digital Assets track.
Finance Loop is a professional network supporting the institutional use of emerging technologies in finance, such as AI, digital payments, cloud and blockchain solutions. Finance Loop helps its members build skills and personal networks in these fields: Investment & Digital Assets, Payments & Digital Money, Digital Infrastructure & Sovereignty, and Risk & Compliance.